
Tear away the glamorous facade of “consumption upgrading,” and you’ll find that the vast majority of new consumption brands falling from grace are, at their core, nothing more than extreme “traffic scalpers.” Their boasted core moats aren’t cycle-crossing supply chains or irreplaceable product formulas, but rather a thoroughly memorized logic of traffic purchasing. To maintain the illusion of high growth and secure the next round of funding, founders throw massive amounts of cold, hard cash at major content platforms like addicts. You think you’re paying for a minimally packaged specialty drink? No. Out of the sixty bucks you pay, forty goes toward the placement fees brands pay to influencers, the product seeding fees for KOLs, and the platform’s traffic-driving costs.
This self-destructive growth model of “drinking poison to quench thirst” has long carried a hidden, astronomical price tag. When the traffic dividend peaks and customer acquisition costs skyrocket exponentially, the once perfectly turning gears instantly jam. Brands suddenly realize that the more they sell, the more they bleed. Stop buying traffic, and sales plummet off a cliff; keep buying traffic, and they become free laborers for the platforms. Let me ask you: how can a company that cannot even generate positive cash flow organically, whose gross margins are entirely devoured by marketing costs, have the audacity to call itself the “pride of domestic brands”?
When the tide goes out, the fig leaves of the naked swimmers are brutally torn away. Those young CEOs who spent their days in the spotlight preaching about “Gen Z mindsets,” “omnichannel marketing closed-loops,” and “private traffic pools” are finally rendered speechless when facing squeezed-to-the-limit OEM factories and e-commerce backends with return rates over 50%. The days of taking a mass-produced water bottle that costs three bucks to make, slapping an “attitude” slogan on it, and having the sheer nerve to sell it for ninety-nine are gone forever. Traffic has never been a moat. When it becomes an expensive life-support drug just to keep vital signs going, the brand has already turned into a breathing commercial zombie.
What truly pushed these new consumption brands into the abyss, besides their distorted reliance on traffic, is the collective arrogance and delusion founders fell into while hijacked by capital. At the peak of the hot-money surge, capital didn’t want a century-old shop that could steadily earn slow money for decades. It wanted a sexy story that could rapidly inflate its GMV within three years and ring the bell in the US or Hong Kong stock markets. Thus, you witnessed highly twisted commercial spectacles: a bakery brand that, instead of studying the fermentation time of flour, spent every day staring at screens in the office analyzing price-to-sales ratios; an underwear brand that hadn’t even solved the fabric pilling issue, yet dared to benchmark itself against Lululemon in its business plan, shouting slogans about redefining female freedom.
Force-ripened by capital, this group of entrepreneurs completely lost their fundamental reverence for the laws of business. Armed with tens of millions in Series A funding, their first move wasn’t to secure factories with the best production capacity, but to rent the most expensive office spaces in core business districts, spend heavily on top-tier international design teams for visual identities (VI), and blindly roll out hundreds of direct-sale stores in Tier-1 cities—even without any real repeat purchase rates. This pouring-oil-on-fire style of expansion is essentially a trampling of common sense. They naively believed that as long as they grabbed land fast enough, they could outlast all competitors, eventually form a monopoly, and then harvest the market.
However, the consumer goods market has never been a winner-takes-all gladiator arena like the internet sector. China possesses the world’s largest and most complex supply chain system, meaning any new consumption concept lacking technical barriers will be copied down to its underwear within three months. Just as you spend millions educating the market and cultivating user habits, you turn around to find thousands of white-label factories furiously shipping products to lower-tier markets at a tenth of the price. Capital can buy fleeting scale, but it can never buy the brand trust built over time. When the baton of fundraising drops to the ground, those pseudo-demands kept alive by burning cash instantly burst like bubbles in the sun, without even leaving a crisp echo.
In this brutal elimination game, the most clear-headed referees are actually the very consumers who were once ruthlessly harvested by them. The fundamental reason the pedestals on this trend collapsed is that the middle class, who once willingly paid for “aesthetic justice” and “emotional value,” suddenly decided to stop playing along. The macro-environmental shocks and workplace beatdowns of recent years have delivered the most profound consumer education to this generation of young people. Everyone suddenly woke up: Why should I spend three times the usual price on a box of instant pasta that offers nothing but pretty packaging? Is it just to post on social media to prove I’m living a refined life?
The greatest arrogance of new consumption brands lies in their attempt to use ethereal marketing rhetoric to mask the extreme thinness of their products’ actual value. They invented countless dazzling buzzwords—”zero sugar, zero calories,” “plant-based,” “Morning C, Evening A”—trying to forcefully superimpose so-called “middle-class added value” onto basic categories. But reality is cold, and the wallets of the working class are honest. As “consumption downgrading” becomes an irreversible zeitgeist, people are ruthlessly stripping away those artificially inflated brand premiums and returning to the most essential utility value of products. It’s not that we can’t afford it; it’s that the marketing gimmicks treating consumers like lambs to the slaughter have genuinely become disgusting.
This isn’t a simple consumption downgrade; it’s a roaring upgrade in consumer intelligence. People are enthusiastically seeking out affordable dupes, directly contacting OEM factories on 1688, and scrutinizing chemical ingredients on nutritional labels. When consumers become more professional than product managers, those new consumption brands that only know how to play tricks with packaging boxes naturally become the first outcasts to be abandoned by the times. Behind their fall from grace is a collective mutiny by an entire generation of youth against pseudo-refinement—a resounding slap in the face to those merchants who tried to drain ordinary folks’ wallets with “IQ taxes.”
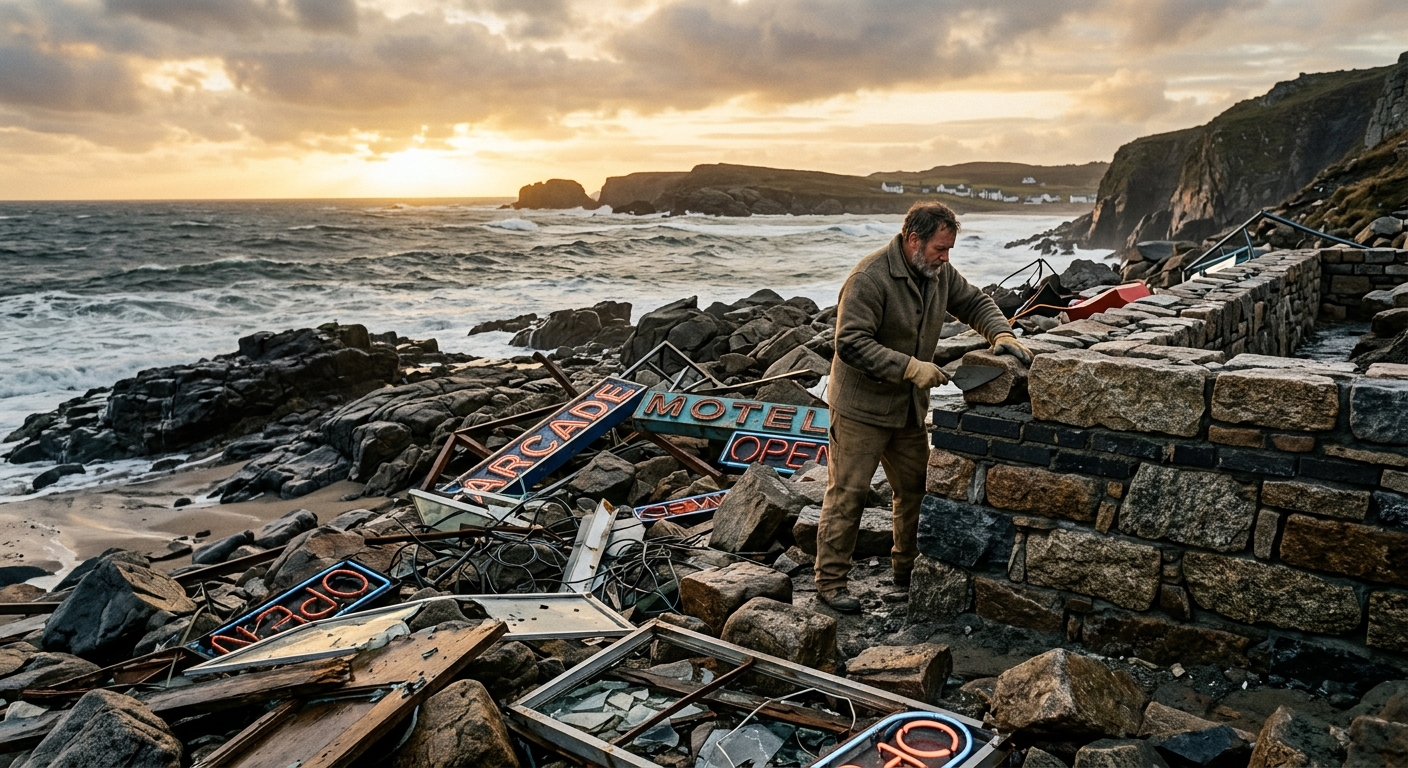
When the howling winds of the era finally die down, the only things left on the beach will be the stubborn stones that can withstand the year-round scouring of the sea. This great capital retreat in new consumption is by no means the end of China’s retail industry; it is a thoroughly satisfying industry-wide cleansing. It has ruthlessly eliminated the opportunists trying to take shortcuts, returning limited resources and survival space to the true pragmatists—those who understand how to obsess over supply chains, respect every penny of profit, and genuinely create value for consumers.
Those falling from the pedestal are the PowerPoint masters who treat running a business like manipulating data, the marketing geeks hopelessly addicted to traffic games. Those who can truly rise again from the ruins will inevitably be the lone warriors who remained restrained during the most frenzied capital crazes, pouring every cent into R&D labs and factory assembly lines. They might not have beautiful data curves, and they might never master that pretentious internet jargon, but they know exactly what bones to use to simmer a good bowl of noodle soup, and they know the collar of a good shirt shouldn’t warp after ten washes. This is the most unadorned, yet most indestructible underlying logic in the business world.
There are no permanent trends, only permanent needs. When the bubble of new consumption is completely squeezed and shattered, we can finally see clearly: a brand is never a firework bought overnight with cash, but a Great Wall that requires generations to pour their blood and sweat into building. The retreat of capital is not a tragedy, but a highly necessary exorcism. It washes away the superficial glamour of the Chinese consumer market, telling all latecomers an ironclad truth: whoever treats consumers like fools will be turned into a true joke by the times. Those false gods who crashed and burned will ultimately become the most vivid fertilizer for this land, nourishing the next wave of great Chinese brands that can truly go global.
—— THE END ——
Honestly, we all saw this coming since late ’24, but seeing it laid out like this really drives home how much waste there was. The focus on “storytelling” over actual unit economics was a fever dream that lasted way too long. Glad we’re finally getting back to basics in the retail sector—burning cash for “traffic” just doesn’t cut it anymore in 2026.
Honestly, seeing these brands fold one by one this quarter isn’t even surprising anymore. We spent way too long subsidizing “lifestyle” habits that never had a path to profitability. The 2024-2025 shakeout was just the beginning—now we’re seeing who actually has a real supply chain and who was just burning VC cash on fancy packaging. Cash flow is finally king again.
It’s been a rough ride since last winter. I think the industry really needed this wake-up call though. For too long, “new consumption” just meant “over-packaged and venture-funded.” Seeing brands finally forced to focus on their supply chains and unit economics here in 2026 is a refreshing, if painful, change. The era of buying growth with pure cash is officially dead.
It’s been a massive reality check for everyone in the industry lately. Looking back at how much cash was burned in ’24 and ’25 just to acquire “loyal” customers who were really just hunting for discounts… well, the chickens have finally come home to roost. The current phase is brutal, but honestly, it’s the only way we’re getting back to actual product value instead of just selling “lifestyle” dreams on VC money.
Really interesting take on how venture capital is pulling back from niche consumer brands. I noticed the same trend in my own circle—several DTC startups I followed last year are now scaling back ads. The author’s data on retail foot traffic was spot‑on. Would love to see a follow‑up on how regional players are filling the void. Honestly, it felt like reading a market report while waiting for my coffee.
I found the analysis on shifting consumer bases compelling, especially the part about mid-tier brands losing share. However, I wonder how the authors accounted for regional differences in spending habits—did they adjust for purchasing power parity? Would love to see a follow‑up with more granular city‑level data.
The piece does a good job tying the recent slowdown in luxury retail to broader capital flight trends. I’ve noticed similar shifts in my own city—high‑end stores are seeing fewer foot traffic while discount chains are picking up steam. It would be interesting to see data on how much of this is driven by actual consumer sentiment versus investors reallocating assets. Still, the analysis feels grounded and worth a deeper dive.
I found the piece compelling, especially how it ties the recent slowdown in luxury spending to shifting venture capital flows. The data on consumer confidence spikes in Q1 2026 supports the thesis, though I wonder if regional disparities in emerging markets were fully accounted for. Overall, a thought‑provoking read that matches what I’ve seen in my own retail analytics work.
The piece does a good job of laying out how venture money is pulling back from the flashy “new consumption” startups we’ve seen over the past couple of years. I’ve noticed similar trends in my own network—friends who used to splurge on subscription boxes and experiential apps are now tightening budgets and opting for more essential goods. It feels less like a sudden crash and more like a market correction that’s forcing these companies to prove real, sustainable value rather than just hype. Worth watching how they adapt their models in the next few months.
The piece nails the shift in discretionary spending as tighter credit bites—really echoes what I’ve seen in my own Q1 2026 sales figures. A deeper dive into which sub‑categories are holding up would be great. Solid read.
Hey, interesting read. I’ve noticed similar capital shifts in the luxury retail space lately—brands that relied heavily on hype-driven sales are seeing investors pull back as discretionary spending cools. It’d be useful to see more data on how mid‑tier players are faring versus the pure‑play luxury names. Thanks for shedding light on the mechanics behind the exodus.
Ha, indeed, 6, feeling good. The article does a solid job tracing how quickly capital can reverse when the consumption hype cools—makes me think of the recent pullback in luxury retail stocks. Worth a read.
The piece does a good job pulling back the glossy veneer of today’s consumption trends and highlighting where capital might flee when the bubble pops. I especially appreciated the concrete examples of discretionary spending shifts. My only curiosity is how much regional variation was factored in—does the exodus look similar across emerging markets versus developed ones? Overall, a thought‑provoking read that sparked a few good thoughts over my morning coffee. Ha, yeah, it feels good.
Read the piece this morning on June 6, 2026. The way you tied the recent slowdown in luxury spend to the shift of capital toward essentials feels spot‑on. I especially liked the data point about the 12% drop in discretionary credit‑card usage in Q1—makes the argument concrete. Still, I wonder if the regional differences in emerging markets got enough weight; a quick look at Southeast Asia shows a different pattern. Overall, a thoughtful read that got me thinking about my own portfolio adjustments.
The article hits on a real tension I’ve noticed in the data—household savings are up while luxury spending growth has slowed to just a few percent year‑over‑year. It feels less like a sudden consumption collapse and more like a broader deleveraging wave as households reset their balance sheets after years of easy credit. A deeper look at regional breakdowns would help pinpoint where the pressure is strongest.
The article highlights a real shift—VCs are pulling back from glitzy consumer apps as the hype fades. I’ve noticed a few peers moving toward B2B SaaS or niche health‑tech, which seem to hold steadier funding. Still, I wonder if the “exodus” is a bit exaggerated; some pockets still attract serious cash despite the broader pull‑back. Would love to hear what others are seeing on the ground.